Retirement Fund Warning: Withdrawal Rates Exceed Projections as South Africans Draw on Two-Pot Savings
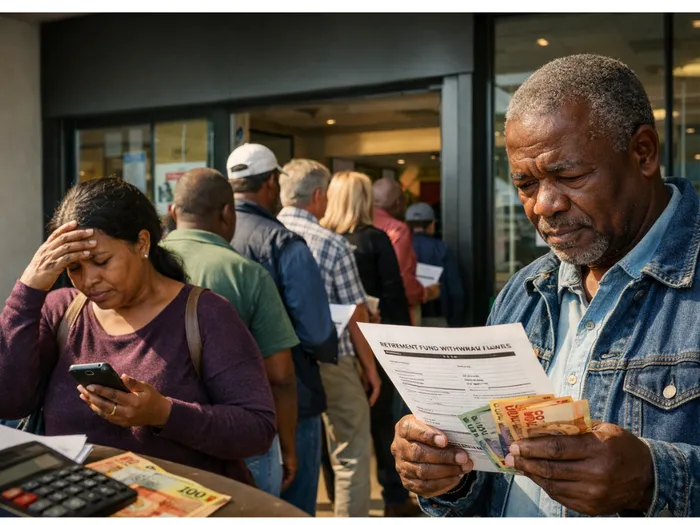
Image Source: IOL
By Sipho “The Investigator” Ndlovu | EZA News
Financial advisers and retirement fund administrators are sounding an increasingly urgent alarm about the pace at which South Africans are drawing down their retirement savings under the two-pot system – a rate of withdrawal that, early data suggests, is significantly outpacing the projections used to design the policy framework.
The two-pot retirement system was introduced to allow fund members limited pre-retirement access to a savings component while preserving a retirement component that cannot be touched before retirement. The logic was sound in principle: provide a pressure valve for genuine financial emergencies without allowing wholesale dismantling of retirement capital. In practice, the evidence emerging from fund administrators indicates that a substantial proportion of members have treated the accessible component as a de facto emergency fund – drawing on it repeatedly and at levels that have surprised even conservative projections.
The implications compound across time. Each withdrawal permanently reduces the capital base available for retirement income, and the effects of reduced compounding over multi-decade investment horizons are not immediately visible to the member making the decision. The consequence – significantly reduced retirement adequacy for a cohort of South Africans who are already likely to face income inadequacy in old age – is a slow-moving crisis that will become acute for individuals but will also place structural pressure on South Africa’s social grant system decades from now.
The warning is particularly pointed for members in the public sector and municipal environments, where the pension fund misappropriation crisis – R1.7 billion in diverted contributions confirmed this week – adds an additional layer of risk to already stretched retirement security. Administrators are urging all members to request updated benefit statements, verify that employer contributions are being correctly processed, and seek independent financial advice before making any further withdrawals.
About The Author